Japan is emerging as one of Asia-Pacific’s most active markets for direct investment in data centres, as demand from hyperscale AI and cloud computing meets increasingly constrained power and land supply across the region, according to a new report.
Data centres are increasingly being assessed as critical digital infrastructure, with secure power, connectivity and operating capability carrying greater weight in investment decisions. Asia-Pacific is expected to add 24 gigawatts of data centre capacity between 2025 and 2030, representing an estimated US$286 billion of real assets value, the Asia Pacific Real Assets Association ( Aprea ) says in a white paper, Wired to Grow: Asia’s Data Centre Reckoning.
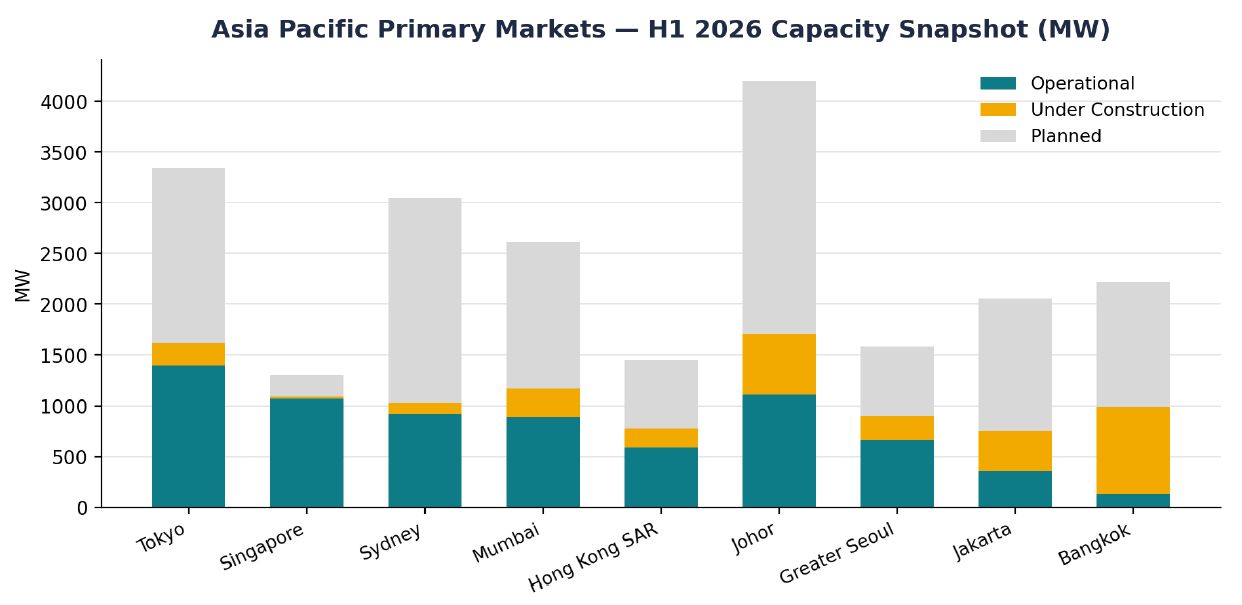
Source: Aprea white paper; Cushman & Wakefield, Asia Pacific Data Centre H1 2026 Update
Japan stands out in recent transaction activity. According to MSCI, transactions for data centres have reached US$11.6 billion since 2024. In 2025, Japan was the second most active market for direct data centre transactions globally, ranking behind only the United States.
“Japan’s position reflects the depth of its digital economy, institutional market and continued demand for high-quality, stabilized infrastructure,” says Aprea chief executive officer Sigrid Zialcita. “But the investment story across Asia-Pacific is becoming more geographically diverse as power availability and capacity determine where new facilities can be delivered. For investors, understanding the differences between established hubs and high-growth markets will be increasingly important in assessing risk, pricing and long-term asset relevance.”
Demand drivers are also shifting. Cloud computing remains the foundation of data centre demand, while AI is creating higher power densities and new requirements for cooling and electrical infrastructure. Aprea’s research notes that AI inference is expected to become the dominant AI workload around 2027, supporting a broader network of hyperscale campuses, established connectivity hubs and facilities closer to end users.
Singapore illustrates the region’s supply dilemma. According to the report, the city-state’s connectivity, regulatory clarity and established ecosystem continue to attract capital, even as constraints on power, land and new supply limit the pipeline of investable opportunities.
These constraints are supporting activity in neighbouring Johor, Malaysia, which has emerged as a major data centre market, supported by greater land and power availability, lower development costs and spillover demand from Singapore.
India is also emerging as one of the region’s most compelling growth markets, with its vast digital economy, accelerating cloud adoption, AI ambitions and data-localization requirements driving demand across Mumbai, Bengaluru, Delhi and Chennai.
Greater China, meanwhile, is emerging as the region’s contrarian data centre investment story. Mainland China is in a repricing and absorption phase, with hyperscale cap rates of 8% in Beijing and 7.8% in Shanghai, while Hong Kong continues to attract large institutional transactions, including a US$2.7 billion data centre partnership.


